Quick answer: a car loan’s cost depends on the amount, APR and term. A longer term lowers your monthly payment but can cost you thousands more in interest, so compare the APR and the total cost, not just the payment. Getting pre-approved before you visit the dealer helps you compare.
For many families, a car is the second-biggest purchase after a home — and the loan can cost thousands of dollars more than it should if you only look at the monthly payment. Here’s how auto loans work and how to pay less.
Auto loan basics
Amount: the car’s price minus your down payment and any trade-in value.
APR: the annual rate, including interest and certain fees.
Term: how many months you’ll take to repay (36, 48, 60, 72…).
The car is collateral: if you stop paying, the lender can repossess it.
The costliest mistake: stretching the term
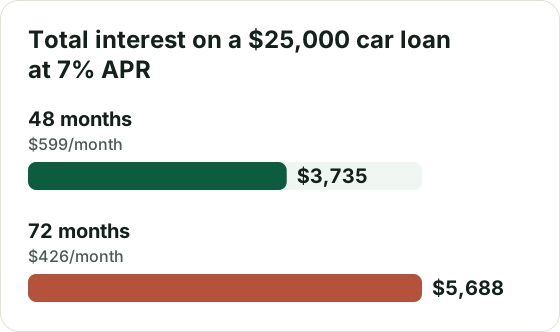
A longer term lowers the monthly payment but raises total interest. Look at this example with $25,000 at 7% APR:
48 months: about $599 a month and $3,735 in interest.
72 months: about $426 a month and $5,688 in interest.
Paying $173 less a month costs you almost $2,000 more in total. And with long terms it’s easy to end up upside down — owing more than the car is worth, because cars lose value quickly.
How much your credit matters
Your rate depends heavily on your score. With the same $25,000 loan over 60 months:
A down payment helps too: putting $5,000 down, so you borrow $20,000 over 60 months at the same rate, saves about $940 in interest and lowers your payment by about $99 a month.
FAQ
Is dealer financing or bank financing better?
There’s no fixed answer: manufacturers sometimes offer great promotions (even 0%). What matters is having your own offer to compare.
Can I pay off my car loan early?
Most auto loans allow it without penalty, but confirm before you sign.
Can I get a car loan with no credit history?
It’s possible, but at higher rates. A co-signer with good credit or a bigger down payment can help.
This article is for educational purposes only and is not financial advice. Figures are illustrative; actual rates depend on your credit, the vehicle and the lender. Read our Disclaimer.
How to find a credit-builder loan near you: credit unions, community banks, CDFIs and online lenders, what each costs, what to ask and how to tell if one is worth it.